
 Financial Investment


 Tiếng Việt
Vietnam requires $1.5 trillion to fuel growth: Banks must evolve from lenders to capital mobilizers
Vietnam will need roughly USD 1.5 trillion in investment between 2026 and 2030 to pursue double-digit growth. Yet bank credit already stands at around 148% of GDP, while the corporate bond market remains modest. The real challenge is therefore not simply how to raise more capital, but how to rewire the way capital flows through the economy.
That question framed the presentation of Mr. Nguyen Huu Hieu, CEO of FiinGroup at the Vietnam Digital Financial Security Forum 2026, organized bythe National Cybersecurity Association (NCA)in Ho Chi Minh City on 6 – 7 November under the theme “AI and Digital Trust: Building Vietnam’s Financial Security Shield”. In his talk, “Strengthening the Link between Banks and Capital Markets”, Mr. Hieu argued that banks have a major opportunity to move beyond lending. He also joined a panel with representatives of the Vietnam International Financial Centre in Ho Chi Minh City (VIFC-HCMC) and Maybank Securities.
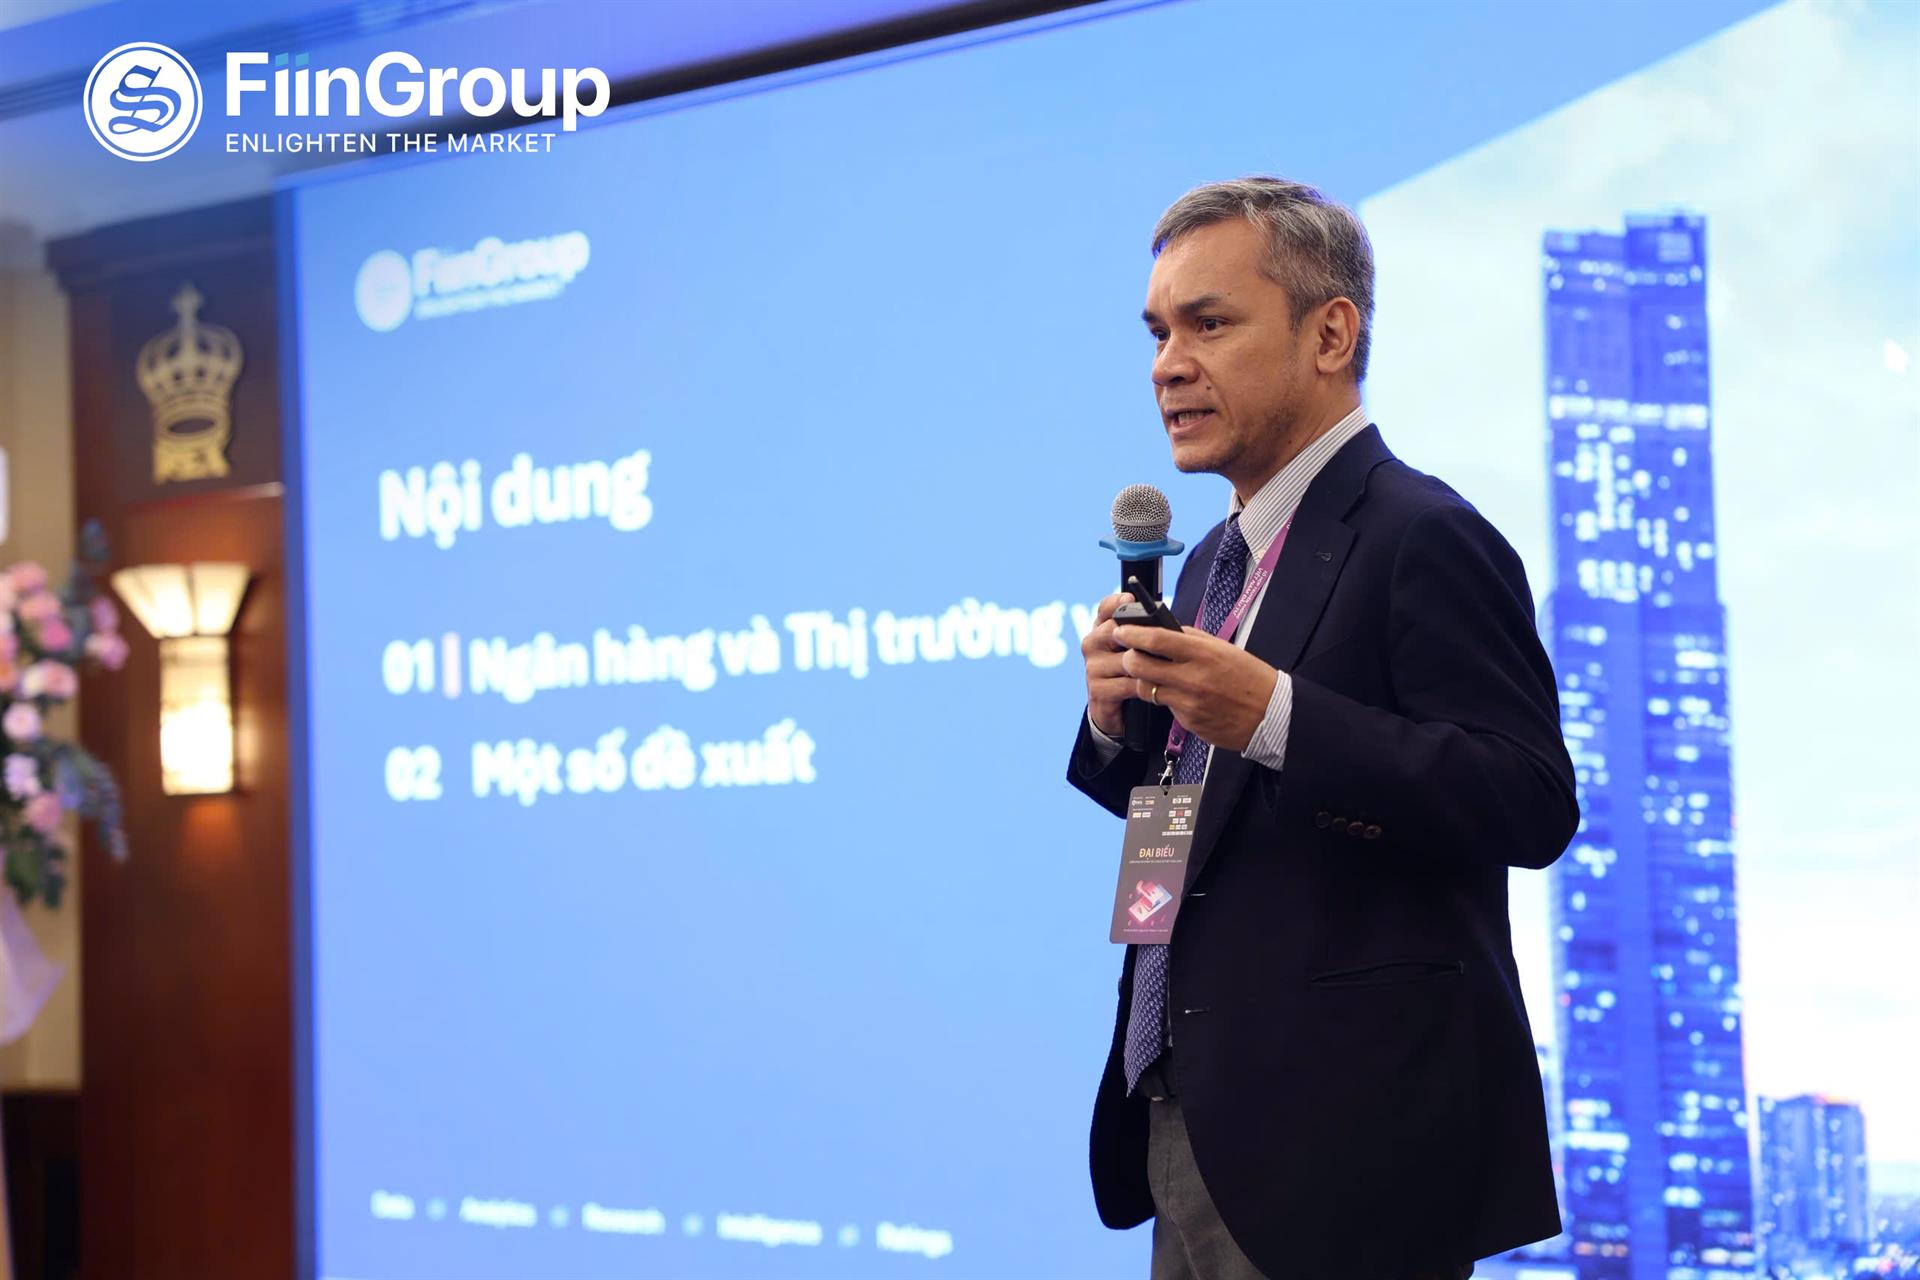
Mr. Nguyen Huu Hieu, CEO of FiinGroup, presenting at the Forum | Mr. Hieu highlighted the opportunity for banks to move beyond lending towards arranging, distributing and connecting long-term sources of capital. Achieving this requires a transparent information foundation, reliable risk assessment mechanisms and deeper participation from institutional investors. |
The USD 1.5 trillion challenge and the limits of the current funding model
FiinGroup and FiinRatings estimate Vietnam’s investment needs for 2026 – 2030 at about USD 1,480 billion, twice the level of the 2021–2025 period. The state budget is expected to cover only around 21%, leaving nearly USD 1,170 billion to be financed by the private sector and the market.
The paradox is that capital needs are long-term, yet the burden of supplying them still falls mainly on banks, which face constraints on maturity, capital and risk appetite. As of 30 September 2026, credit was estimated at about 148% of GDP, comparable to South Korea (160%) and Singapore (133%). By contrast, corporate bonds amount to only about 10% of GDP, compared with 69% in South Korea and 55% in Malaysia (bond data for other markets as of 30 June 2026). In short, Vietnam has the credit depth of a developed economy, but its debt capital market is still at an early stage.
Three factors keep banks at the centre of the system:
A thin institutional investor base. Banks bought 57.6% of new corporate bond issuance by value in 2025. They are also the largest issuers, accounting for 53% of issuance in the first nine months of 2026, while foreign investors account for just 2.6% of corporate bond investors. When the same institutions sit on both sides of the market, risk ends up back on bank balance sheets.
Underdeveloped risk pricing. At end-2024, 57.6% of outstanding corporate bonds paid floating rates, most of them pegged to bank deposit rates. That compares with 7.6% in Malaysia and 3.9% in South Korea. Without bond pricing agencies or a benchmark yield curve, yields fail to reflect credit risk, which makes corporate bonds a poor fit for investment funds and insurers.
Limited corporate information.Many private companies file financial statements late, so lenders still rely more on collateral than on cash flow.
The strain is already visible. At end-2025, the four state-owned commercial banks had a median capital adequacy ratio (CAR) of 9.9%. That is below the 10.5% they are expected to reach as capital buffers under the State Bank of Vietnam’s Circular 14/2025 are phased in. Short-term deposits are also a mismatch for infrastructure loans that run 10 to 30 years. Mr. Hieu warned that domestic capital alone will struggle to meet future needs. With funding concentrated in public investment, private firms, and SMEs in particular, find it hard either to borrow from banks or to issue bonds. He emphasized that Vietnam must open new channels for capital.
Banks in a new role: From lenders to capital mobilizers
The central message of the presentation is that capital market development does not diminish the role of banks. On the contrary, it creates an opportunity for banks to move from lending to organising and connecting capital flows. That transition can be seen as three shifts:
From lending to capital mobilization: leveraging client relationships and credit appraisal capabilities, banks can arrange, support issuance and distribute financial products, connecting businesses with domestic and international investors.
From balance sheet to capital markets: rather than holding long-term loans to maturity, banks distribute risk to capital market investors.
From interest income to fee-based income: as net interest margins (NIM) come under pressure, revenue from arranging, distribution and asset management becomes a new growth driver.
However, the capital relief these models deliver depends on genuine risk transfer and an appropriate legal framework.
Trust infrastructure: a prerequisite for capital market development
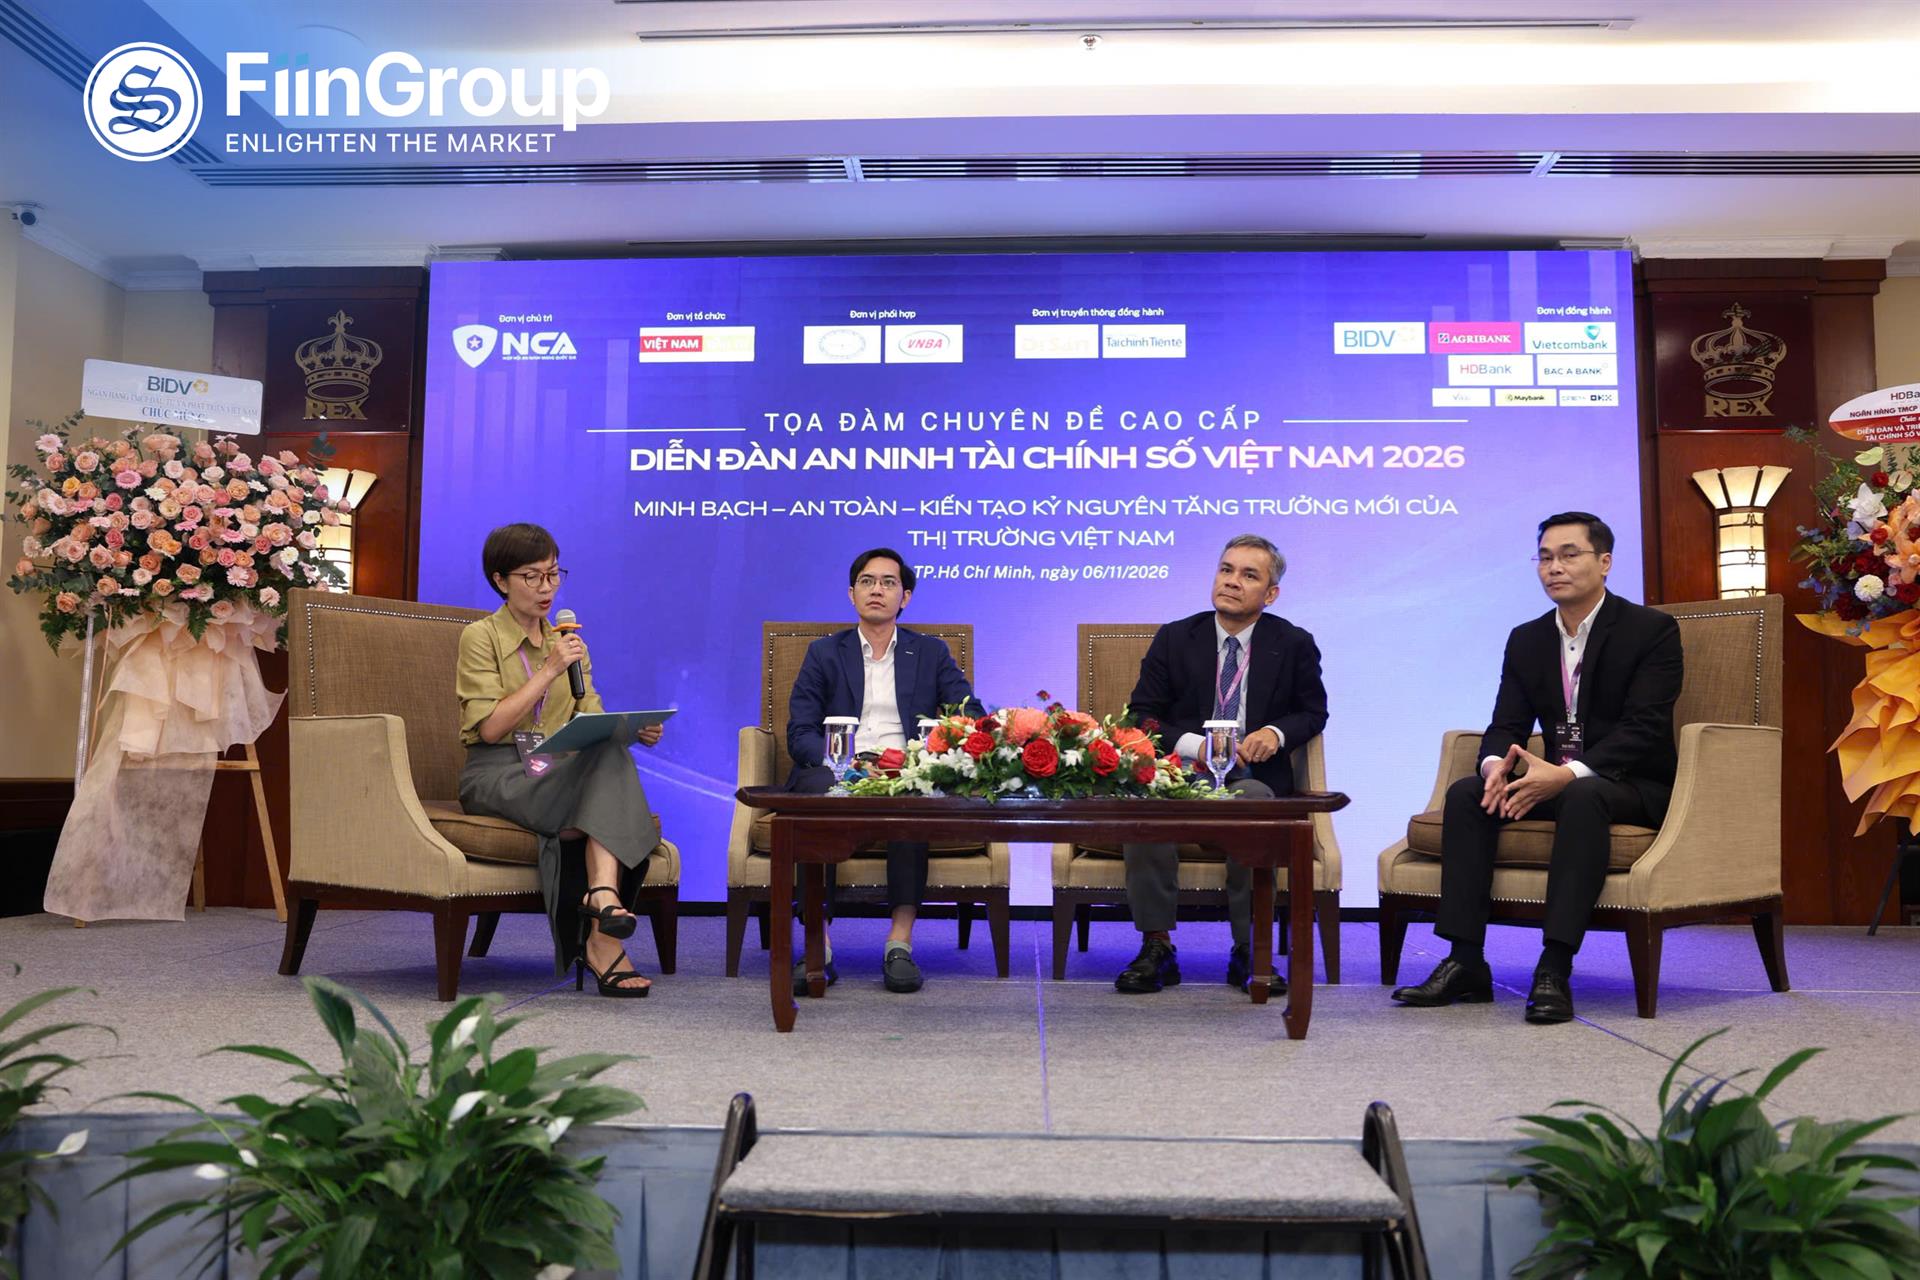
Mr. Nguyen Huu Hieu, CEO of FiinGroup, with representatives of VIFC-HCMC and Maybank Securities at the panel discussion
The Forum’s focus on AI and digital trust offers a useful lens: trust in a financial system rests not only on secure transactions, but on the ability to understand, measure and manage the risks behind capital flows. Secure data is the starting point. For investors to act on it, that data must also be reliable, timely and independently verified.
For international capital, Mr. Hieu noted, meeting the standards investors expect will shape both access to funding and its cost. Those standards include international credit ratings, audits by reputable firms, IFRS reporting, and the involvement of credit enhancement and guarantee providers.
“Attractiveness may draw capital to Vietnam, but only trust will make it stay,”Mr. Hieu said.
From ideas to action
Three systemic proposals stand out from the presentation and panel discussion.
Refinancing infrastructure through the capital market.Banks fund the construction phase. Once a project is operating and generating stable cash flow, the loan is refinanced through project bonds or securitization. Banks free up balance sheet capacity, while funds and insurers gain the long-term assets they need.
Unlocking alternative data for SME lending.SMEs make up 98% of Vietnamese businesses but often lack timely financial information and collateral. With all invoices now issued electronically, lawful access to e-invoice data and national databases could support independent credit scoring based on real business activity. This would allow banks to extend more unsecured credit based on actual cash flows and channel more capital to the private sector.
Building risk-pricing infrastructure.This means independent credit ratings, transaction data, yield curves by sector and rating, and post-issuance monitoring. When yields reflect credit risk, institutional investors have a basis for pricing, and strong issuers can borrow at a cost that matches their credit quality. A broader investor base would also reduce the market’s reliance on banks as the main buyers.
FiinGroup’s role in building the market’s trust infrastructure
FiinGroup provides banks and financial institutions with financial data, in-depth analytics and risk assessment tools for credit appraisal, valuation and portfolio monitoring. Its capabilities are built on the FiinPro-X - Financial Data Platform & Bond Portal, bond pricing services, corporate risk scoring solutions, and market research.
FiinRatings, a FiinGroup member company and strategic partner of S&P Global, operates independently, providing credit ratings under a licence from the Ministry of Finance and independent green bond assessments. Guided by an AI-first strategy, FiinGroup continues to build data and knowledge infrastructure that makes information more useful in day-to-day decision-making. Working alongside other market participants, FiinGroup aims to strengthen transparency and trust in Vietnam’s capital markets.
👉 Read the full presentation HERE
---------------------------------
Explore FiinGroup’s solutions for banks
☎️ +84 (24) 3562 6962


